In short
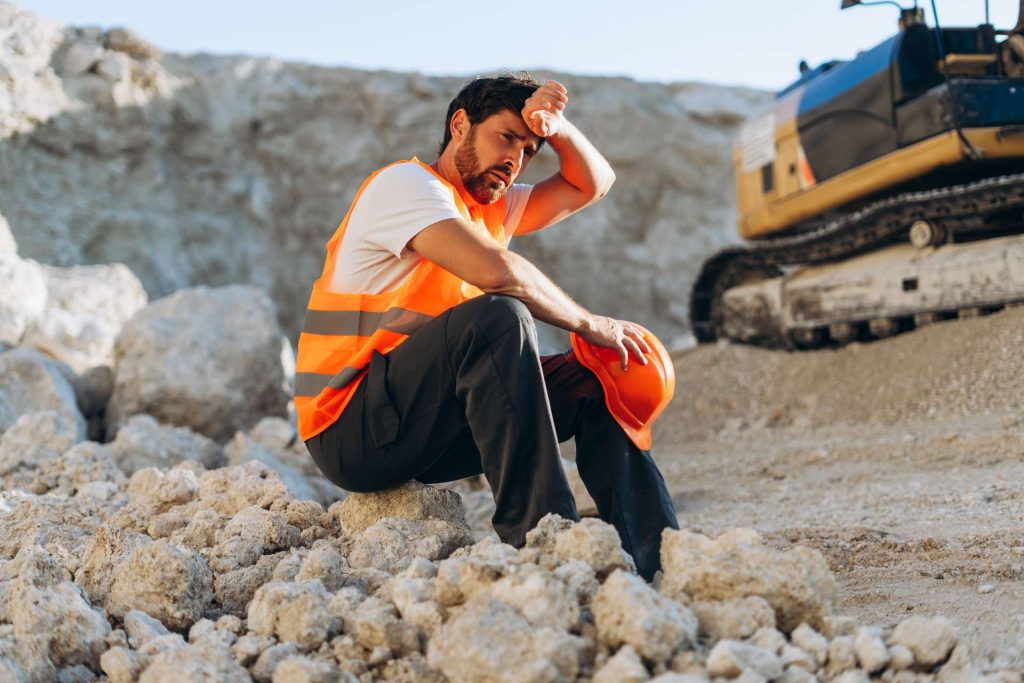
Yes, miners can get income protection, although insurers give high-risk roles a more detailed assessment based on your actual duties, work location, type of operation and health. It generally covers most illnesses and injuries that stop you working, at work or away from it, but not redundancy or voluntary unemployment. Waiting periods commonly range from 14 to 90 days, and benefit periods from two years to age 65.
Working in mining means facing risks that office workers rarely encounter. Underground environments, tunnels, shafts, and heavy machinery on the surface are part of daily work, which makes income protection a concern that likely crosses your mind more often than you care to admit.
Understanding Income Protection for Mining Roles
Income protection provides a regular income during illness or injury. Given mining’s high-risk nature, this cover is especially important. Mining roles involve hazards such as respiratory risks, tunnel collapses, environmental exposure, and heavy machinery. High-risk roles receive a more detailed assessment from insurers.
How Insurers Assess Mining Roles
Insurers assess the actual work performed each day, as mining roles carry different risk levels. Premiums reflect specific duties rather than job titles alone. Underground work, surface operations, and administrative roles each present distinct risk profiles, leading to different assessments. Key factors insurers consider include:
- Your role and daily tasks
- Underground or surface work location
- Type of mining operation
- Work environment and safety measures
- Overall health and medical history
Why Income Protection Matters for Miners
Mining often offers higher pay than urban jobs, but living costs in remote locations can be steep. Illness or injury halts income, and workers’ compensation covers only work-related incidents. Income protection replaces a portion of earnings, helping miners stay financially secure.
What’s Typically Covered?
Income protection for miners generally covers most illnesses and injuries that prevent you from working, including:
- Musculoskeletal injuries from manual handling or accidents
- Respiratory conditions
- Mental health conditions, including stress-related illness
- Injuries sustained both at work and away from work
- Serious illnesses requiring extended recovery periods
It’s worth noting that income protection doesn’t cover redundancy or voluntary unemployment. It’s specifically designed to protect you when health issues prevent you from earning an income.
Getting the Right Coverage
Finding appropriate income protection as a miner requires working with advisers who understand your industry. The mining sector has unique characteristics that generic insurance approaches often miss.
Waiting Periods
Common waiting periods range from 14 days to 90 days, with longer waiting periods typically resulting in lower premiums.
Benefit Period
Options typically range from two years to age 65, depending on your circumstances and budget.
Own Occupation vs Any Occupation
Own occupation coverage pays out if you can’t perform your specific mining role. On the other hand, any occupation only pays if you can’t work in any job suited to your education and experience.
Premium Structure
Stepped premiums start lower but increase with age, whereas level premiums remain more consistent over time.
A mining career brings financial rewards but also risks to your income. Income protection safeguards your earnings and your family’s future. At Absolute Insurance, we help Western Australian miners secure coverage tailored to their roles. Contact us today for personalised advice and protection that fits your lifestyle.
Related posts:
- Can You Get Life Insurance for Underground Miners?
- Hidden Risks Every Miner Faces and How to Insure Against Them
- The Importance of Life Insurance for Miners
Reviewed by Greg Maguire
Greg Maguire reviewed this article to make sure the information is accurate and reflects current insurance practice. It is general advice only and does not take your personal circumstances into account.
Greg Maguire is an Authorised Representative (No. 255354) of AD Advisory Services Pty Ltd, ABN 68 005 830 802, AFSL 237058.
Related Services
Insurance for Teachers
Insurance for Teachers →
Insurance for Construction Workers
Insurance for Construction Workers →
Insurance for Healthcare Workers
Insurance for Healthcare Workers →
Insurance for FIFO Workers
Insurance for FIFO Workers →
Insurance for Miners
Insurance for Miners →
Insurance for Tradies
Insurance for Tradies →
Related Articles