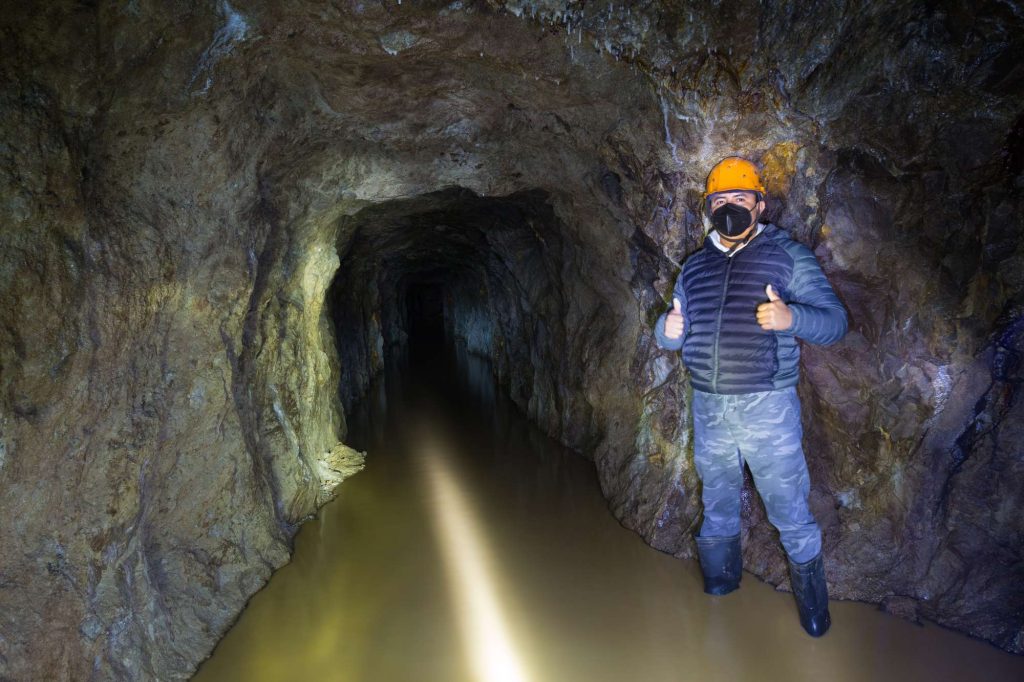
In short
Yes, many insurers in Australia still offer life insurance to underground miners, but underwriting may be more detailed and premiums higher. Insurers look at your specific role, the type of mine, safety protocols and your health, and may apply exclusions or at times decline cover. Default cover in super may not be enough for families who rely on a miner’s income, and because insurers assess risk differently, comparing providers can help.
Working as an underground miner comes with inherent risks and hazards, making safety a top priority across the mining sectors in Western Australia. Amidst rigorous safety measures and regulations, there remains an undeniable truth that this occupation entails significant risk factors. An important aspect of financial planning for those in this field is considering life insurance. Ensuring that miners and their families are protected against unforeseen events can be crucial. So, can you get life insurance as an underground miner? Let’s explore.
Understanding Life Insurance
Life insurance is a contract between an insurer and a policyholder, where the insurer commits to pay a designated beneficiary a sum of money upon the death of the insured person, in exchange for premium payments. This financial safety net is imperative, especially for high-risk occupations, providing peace of mind and financial security for families depending on the miner’s income.
However, for those in high-risk occupations, such as underground mining, obtaining life insurance can entail additional complexities. Insurers assess applicants’ risks based on various factors, including their occupation, health, lifestyle, and more. Understanding these parameters can greatly aid miners in navigating the insurance market.
The Challenges of Insuring Underground Miners
Underground mining is recognised as one of the more hazardous professions due to various factors like exposure to dust and chemicals, the potential for accidents, and other occupational hazards. Consequently, life insurance underwriters often classify such occupations as high-risk, influencing both the availability of insurance and premium costs.
When underwriting a life insurance policy, insurers conduct thorough assessments. This includes evaluating the risks associated with the specific duties of the miner, their work environment, along with their personal health history. Miners face the possibility of higher premiums, exclusions of certain events from coverage, or at times, even denial of coverage.
However, this isn’t a universal situation. Different insurance companies may evaluate risk factors differently. Therefore, it’s essential for miners to work with knowledgeable brokers or advisors who understand the risks and can assist in negotiating the best possible terms tailored to their unique circumstances.
Options and Considerations
Despite the challenges, underground miners do have several options when it comes to life insurance. Group insurance provided by some employers can be a viable option, often offering coverage that’s more affordable and accessible than individual policies. However, these policies might not be customisable to the specific needs of the miner’s family and might not offer adequate cover.
Another route might be seeking particular insurers who specialise in high-risk occupations. Such insurers will have a more nuanced understanding of the mining profession and potentially offer more tailored options suitable for miners. It is beneficial to obtain quotes from multiple providers to ensure a comprehensive view of the available options.
Before making a decision, miners should carefully scrutinise the terms of coverage, including any exclusions, limitations, or particular conditions set by the insurer. Full disclosure of one’s work conditions and hazards is crucial to ensure that the policy remains void of potential grounds for claim disputes.
Life insurance is undeniably a critical component of financial planning for underground miners in Australia. At Absolute Insurance, we specialise in helping individuals in high-risk occupations navigate the complexities of obtaining life insurance. Our team is dedicated to providing personalised advice and finding the right coverage to suit your needs. Contact us today to explore your options and ensure peace of mind for you and your loved ones.
Frequently Asked Questions
1. Can underground miners still qualify for life insurance despite the risks?
Yes. While underground mining is considered a high-risk occupation, many insurers in Australia still offer life insurance to miners. The key difference is that the underwriting process may be more detailed, and premiums may be higher to reflect the occupational risk.
2. Will working underground automatically increase life insurance premiums?
In many cases, insurers apply an occupational loading to premiums for underground miners. The exact increase depends on factors such as your specific role, the type of mine you work in, safety protocols at your workplace, and your overall health profile.
3. Do FIFO underground miners qualify for life insurance?
Yes. FIFO workers can qualify for life insurance, but insurers may assess additional factors such as travel patterns, shift rotations, and the physical demands of the role. Being a FIFO worker alone does not usually prevent approval.
4. Is life insurance through superannuation enough for underground miners?
Default life insurance inside superannuation can provide a basic level of protection, but it may not be sufficient for families who rely heavily on a miner’s income. Many miners choose to supplement their superannuation cover with additional policies to ensure their dependants are adequately protected.
5. Can miners apply for insurance if they already have health issues related to their work?
Yes, although the application may require additional medical information. Insurers may request medical reports or apply specific exclusions related to pre-existing conditions. A broker can help identify insurers that are more flexible in these situations.
6. Does the type of mining role affect insurance eligibility?
Yes. Insurers often differentiate between roles within the mining industry. For example, a mine manager or engineer working partly underground may be assessed differently from a miner performing physically intensive underground tasks every day.
7. Can underground miners switch life insurance providers later?
Yes, it is possible to change insurers if better cover or pricing becomes available. However, switching policies may require a new underwriting assessment, so it’s important to review the new policy carefully before cancelling any existing cover.
8. How can a broker help underground miners find the right cover?
An experienced insurance broker understands which insurers are more open to high-risk occupations and can compare multiple policies on your behalf. This can help miners find suitable cover while avoiding unnecessary exclusions or excessive premiums.
Related posts:
- Hidden Risks Every Miner Faces and How to Insure Against Them
- The Importance of Life Insurance for Miners
- What Waiting Periods Do Miners Have on Their Life Insurance?
Reviewed by Greg Maguire
Greg Maguire reviewed this article to make sure the information is accurate and reflects current insurance practice. It is general advice only and does not take your personal circumstances into account.
Greg Maguire is an Authorised Representative (No. 255354) of AD Advisory Services Pty Ltd, ABN 68 005 830 802, AFSL 237058.
Related Services
Insurance for Teachers
Insurance for Teachers →
Insurance for Construction Workers
Insurance for Construction Workers →
Insurance for Healthcare Workers
Insurance for Healthcare Workers →
Insurance for FIFO Workers
Insurance for FIFO Workers →
Insurance for Miners
Insurance for Miners →
Insurance for Tradies
Insurance for Tradies →
Related Articles