In short
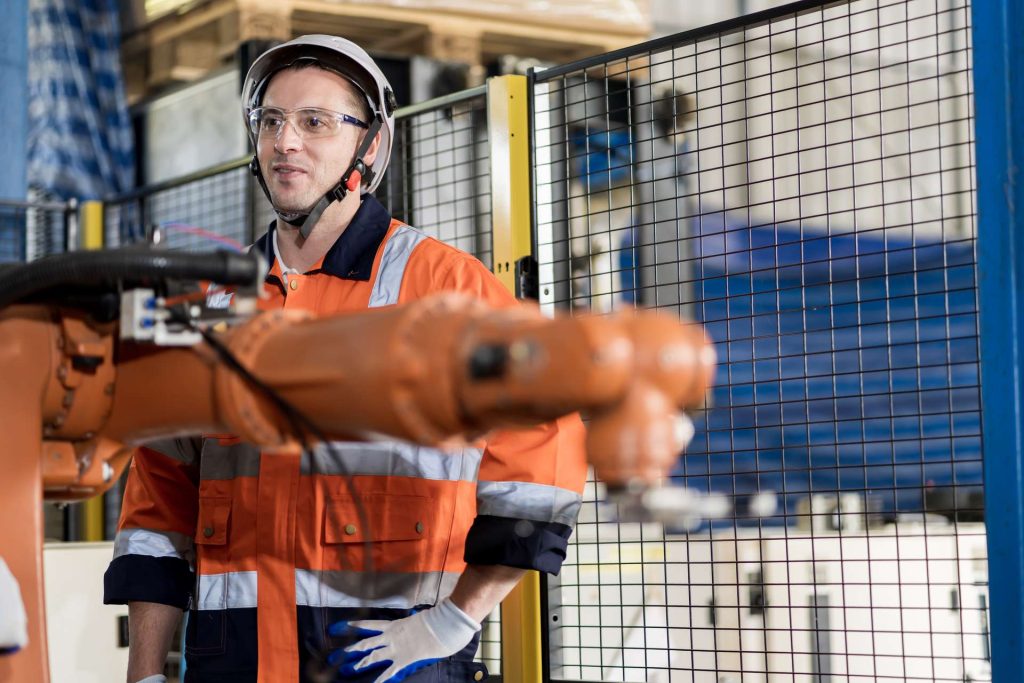
Yes, FIFO workers can qualify for life insurance, but your role, site type, duties, roster and health may affect how insurers assess you and what you pay. Office-based roles are generally seen as lower risk, while hands-on roles such as drilling or underground work may attract premium loading, though insurers’ criteria differ. Cover through super is a starting point but may not fully cover a mortgage or dependants.
FIFO roles often involve remote locations, long shifts, and physically demanding work. So where does that leave you when it comes to protecting your family’s financial future? The short answer is yes, FIFO workers can absolutely qualify for life insurance. However, your occupation and work environment may influence how insurers assess your application and what premiums you’ll pay.
How Insurers View FIFO Work
Life insurance providers assess risk based on your occupation, lifestyle, and health. For FIFO workers, insurers typically consider factors such as:
- The nature of your role (office-based versus hands-on labour)
- The type of site you work on (mining, oil and gas, construction)
- Your specific duties and any exposure to hazardous conditions
- Your roster pattern and time spent on-site
- Your overall health and any pre-existing conditions
Office-based FIFO roles, such as administration, HR, or management positions, are generally viewed as lower risk. Hands-on roles like heavy machinery operation, drilling, or working underground may be classified as higher risk, which can affect your premium.
What About Premium Loading?
Depending on your role, you may face premium loading, where your insurance costs more due to higher occupational risk. Not all FIFO workers are affected, as insurers have different criteria. An experienced insurance adviser can help you navigate these differences and find the most competitive coverage for your role.
Types of Cover Relevant to FIFO Workers
Life Insurance (Death Cover)
Provides a lump sum to your family or beneficiaries if you die, helping them manage mortgage repayments, living expenses, and future financial needs.
Total and Permanent Disability (TPD) Insurance
Pays a lump sum if you suffer an injury or illness that prevents you from working again. Given the physical demands of many FIFO roles, TPD cover is worth serious consideration.
Income Protection Insurance
Replaces a portion of your income if you’re unable to work due to illness or injury. This can be a financial lifeline if you’re off-site recovering and not earning your usual wage.
Trauma Insurance
Provides a lump sum if you’re diagnosed with a serious illness such as cancer, heart attack, or stroke. It gives you financial breathing room to focus on recovery without worrying about bills.
Superannuation Insurance: A Starting Point
Many FIFO workers already have life insurance through their superannuation fund. Although this can be cost-effective, it’s important to check if the cover is sufficient for your needs. Super-based insurance often provides basic protection, which may not fully cover a mortgage, dependents, or other financial commitments. We can review your existing super insurance and help you determine whether additional cover is needed to properly protect your family.
Getting the Right Cover for Your Situation
Every FIFO worker’s situation is different. Your income, family circumstances, debts, and long-term goals all play a role in determining the right level and type of cover. Our team takes the time to understand your unique needs and compare policies from a range of insurers. We’ll explain your options in plain language, help you weigh up the costs and benefits, and ensure you’re not paying for cover you don’t need or missing out on protection that matters.
Contact our team at Absolute Insurance today for a free, no-obligation consultation. We’ll take the guesswork out of life insurance and help you find a solution that fits your work, your budget, and your peace of mind.
Related posts:
- Crucial Insurance Tips for FIFO Workers in Australia
- What Life Insurance Products Are Needed by FIFO Workers?
- How to Navigate Income Protection Waiting Periods as a FIFO Worker
Reviewed by Greg Maguire
Greg Maguire reviewed this article to make sure the information is accurate and reflects current insurance practice. It is general advice only and does not take your personal circumstances into account.
Greg Maguire is an Authorised Representative (No. 255354) of AD Advisory Services Pty Ltd, ABN 68 005 830 802, AFSL 237058.
Related Services
Insurance for Teachers
Insurance for Teachers →
Insurance for Construction Workers
Insurance for Construction Workers →
Insurance for Healthcare Workers
Insurance for Healthcare Workers →
Insurance for FIFO Workers
Insurance for FIFO Workers →
Insurance for Miners
Insurance for Miners →
Insurance for Tradies
Insurance for Tradies →
Related Articles