In short
- Workers’ compensation typically covers only 70% to 85% of base salary and won’t help with injuries outside work, whereas income protection can cover you wherever it happens.
- Back injuries, hearing damage and respiratory conditions can end a mining career, which is where own-occupation TPD applies.
- FIFO life brings mental health pressures, and income protection can cover mental health conditions that stop you working.
- Default super cover often falls short, with capped benefits and restrictive TPD definitions.
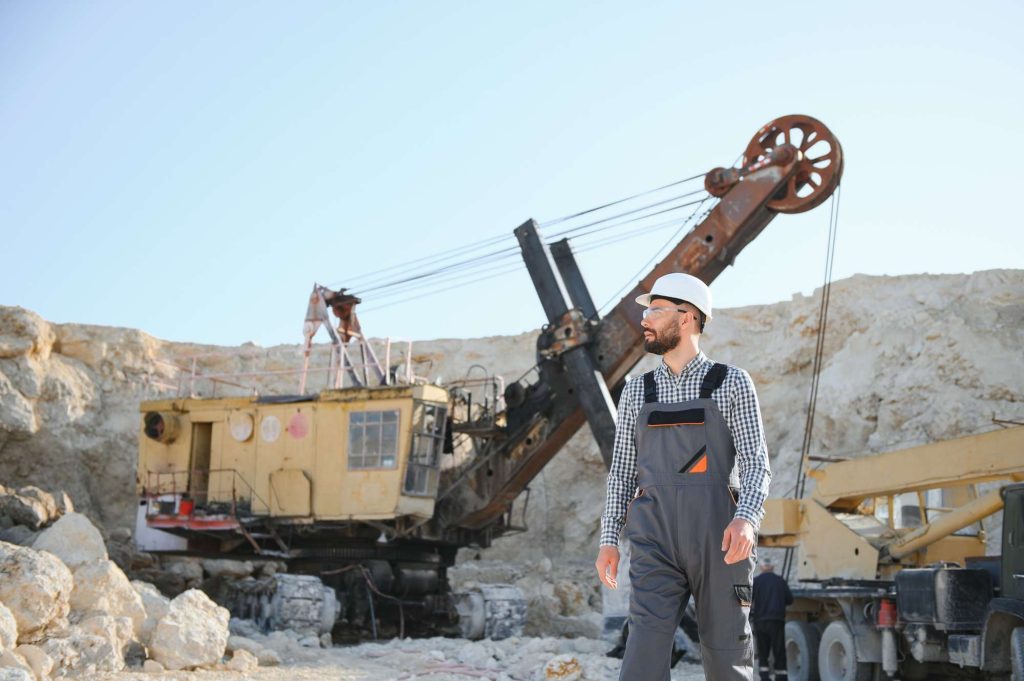
Mining remains one of Western Australia’s economic pillars, but it also presents unique risks that extend beyond the obvious physical hazards. As insurance specialists working with many mining professionals across Perth and regional WA, we’ve identified several overlooked risks that miners should protect themselves against.
Financial Vulnerability During Injury Recovery
The mining sector offers attractive salaries that often support entire families and significant financial commitments. When injury strikes, the gap between workers’ compensation payments and your regular income can create serious financial strain.
Income protection insurance bridges this critical gap. Unlike workers’ compensation, which typically covers only 70-85% of your base salary (excluding overtime and bonuses), comprehensive income protection can:
- Replace part of your total income, including allowances
- Continue payments for an extended period, even until retirement age, for permanent disabilities
- Provide coverage regardless of where the injury or illness occurs
Many miners don’t realise that workers’ compensation won’t help if you’re injured outside work hours or develop a condition unrelated to your employment.
Career-Ending Injuries and Conditions
Mining involves physical demands that make certain injuries particularly devastating to your career prospects. Back injuries, hearing damage, and respiratory conditions can permanently end your mining career, even when they develop gradually over time.
Total and Permanent Disability (TPD) insurance provides a lump sum payment if you become unable to work in your occupation again. For miners, we recommend:
- Own-occupation TPD cover that pays out if you can’t continue in mining specifically
- Policies that recognise the unique physical requirements of mining roles
- Coverage that accounts for the limited transferable skills some specialised mining roles provide
Family Financial Security
The remote nature of many mining operations means longer response times in emergencies. This reality, combined with the inherent risks of the industry, makes life insurance particularly important for mining families.
When structuring life insurance as a miner, consider:
- Higher coverage amounts that reflect your income and family responsibilities
- Trauma insurance add-ons that cover specific conditions common in the industry
- Child trauma coverage to protect your family if you need to take extended time off to care for an ill child
Mental Health Challenges
The FIFO lifestyle creates unique mental health pressures that many miners underestimate. Extended periods away from family, disrupted sleep patterns, and isolation can lead to serious mental health conditions.
Many miners don’t realise that:
- Income protection can cover mental health conditions that prevent you from working
- Some policies offer specific mental health support services
- Trauma insurance can provide lump sum payments for severe mental health diagnoses
Superannuation Insurance Gaps
Many miners assume their superannuation includes adequate insurance coverage. In reality, default super policies rarely provide sufficient protection for high-income mining professionals.
We regularly identify significant gaps when reviewing miners’ existing coverage:
- Default income protection through super often caps benefits well below a miner’s actual income
- Many super TPD policies use restrictive definitions that make claims difficult
- Life insurance amounts are typically insufficient for families with significant financial commitments
As insurance specialists who understand the mining industry, we help miners develop comprehensive protection strategies tailored to their specific roles, income levels, and family situations. Contact Absolute Insurance for a confidential review of your current insurance arrangements. We’ll identify any gaps in your protection and recommend practical solutions that provide genuine security for you and your family.
Related posts:
Reviewed by Greg Maguire
Greg Maguire reviewed this article to make sure the information is accurate and reflects current insurance practice. It is general advice only and does not take your personal circumstances into account.
Greg Maguire is an Authorised Representative (No. 255354) of AD Advisory Services Pty Ltd, ABN 68 005 830 802, AFSL 237058.
Related Services
Insurance for Teachers
Insurance for Teachers →
Insurance for Construction Workers
Insurance for Construction Workers →
Insurance for Healthcare Workers
Insurance for Healthcare Workers →
Insurance for FIFO Workers
Insurance for FIFO Workers →
Insurance for Miners
Insurance for Miners →
Insurance for Tradies
Insurance for Tradies →
Related Articles