In short
- Life insurance pays a lump sum to help your family with the mortgage, living expenses or business debts if you pass away.
- Income protection can replace part of your income if illness or injury stops you teaching.
- Trauma and TPD insurance pay lump sums for a serious illness or a permanent disability.
- Studio owners may also consider business expense, key person, public liability and professional indemnity cover.
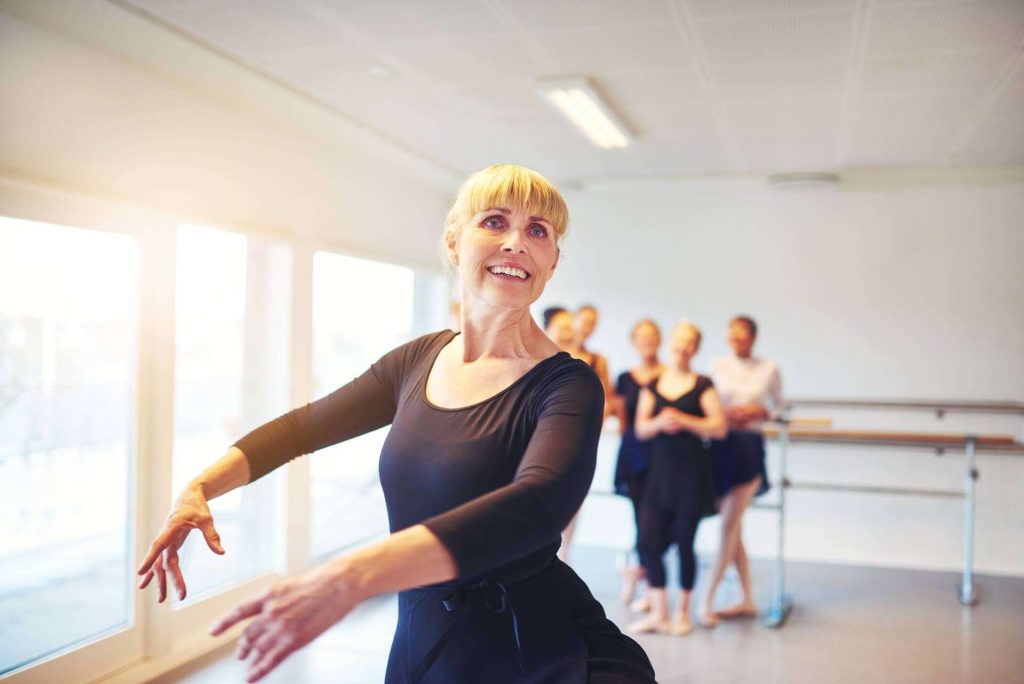
Teaching dance is a calling that combines artistry, physical skill, and the rewarding work of guiding students through their creative journey. Whether you’re teaching ballet to beginners, choreographing contemporary routines, or running your own studio, you’re building something meaningful. But have you considered what would happen to your students, your business, and your family if you were suddenly unable to teach?
For dance teachers across Australia, insurance isn’t only about protecting your studio space or covering a student’s injury. It’s also about safeguarding your most valuable asset: your ability to earn an income and provide for those who depend on you.
Why Life Insurance Matters for Dance Teachers
As a dance teacher, your body is your business. You demonstrate techniques, move constantly throughout the day, and rely on your physical health to earn a living. But what happens if illness or injury prevents you from teaching? Or worse, what if you lost your life unexpectedly?
Life insurance provides financial protection for your loved ones if you pass away, ensuring they’re not left struggling with mortgage payments, living expenses, or business debts. For self-employed dance teachers or studio owners, this protection becomes even more critical, as your income stops the moment you can’t work.
The Reality for Self-Employed Dance Teachers
Unlike employees who might receive sick leave or death benefits through their employer, self-employed dance teachers carry the full financial risk themselves. If you’re the primary income earner in your family, or if you’ve invested significantly in building your dance business, life insurance ensures your family won’t face financial hardship during an already difficult time.
Consider these scenarios:
- You’ve taken out a business loan to open your studio
- Your family relies on your income to cover the mortgage
- You have young children who depend on your financial support
- Your partner would struggle to maintain your current lifestyle on a single income
Life insurance can address all these concerns, providing a lump sum payment that helps your family maintain financial stability.
Income Protection: Your Financial Safety Net
While life insurance protects your family if you pass away, income protection insurance safeguards your income if you become unable to work due to illness or injury. For dance teachers, this coverage is particularly valuable.
Teaching dance is physically demanding. Repetitive movements, demonstrations, and constant physical activity can lead to injuries over time. Common issues affecting dance teachers include:
- Back and joint problems from years of physical activity
- Repetitive strain injuries
- Acute injuries from demonstrations or accidents
- Stress-related conditions from running a business
If any of these prevent you from teaching, income protection insurance can replace part of your income while you recover. This means you can focus on getting better without worrying about how you’ll pay your bills.
Trauma Insurance: Support When You Need It Most
Trauma insurance (also called critical illness cover) pays a lump sum if you’re diagnosed with a serious medical condition like cancer, heart attack, or stroke. For dance teachers, this coverage provides essential support during a health crisis.
A serious illness stops you from earning an income while also creating additional expenses. Medical treatments, specialist consultations, modifications to your home, or even travelling for treatment all cost money. Trauma insurance provides funds to cover these expenses without depleting your savings or forcing your family into debt.
For studio owners, trauma insurance can also provide the breathing space needed to make important business decisions. You might need to hire temporary instructors, reduce your class schedule, or even sell your business. Having financial support gives you options during a difficult time.
Total and Permanent Disability (TPD) Insurance
TPD insurance provides a lump sum payment if you become permanently disabled and can no longer work in your occupation. For dance teachers, whose careers depend entirely on physical capability, this coverage offers essential protection.
TPD policies can be structured as “own occupation” or “any occupation” cover. Own occupation cover pays out if you can’t work as a dance teacher specifically, even if you could do other work. This is particularly relevant for dance professionals, as an injury that ends your teaching career might not prevent you from doing sedentary work.
The lump sum from TPD insurance can help you:
- Pay off your mortgage and other debts
- Retrain for a new career
- Modify your home for accessibility
- Maintain your family’s lifestyle
- Cover ongoing medical expenses
Business Expense Insurance: Keeping Your Studio Running
If you own a dance studio, business expense insurance can cover your ongoing business costs if you’re temporarily unable to work due to illness or injury. This includes expenses like:
- Rent or mortgage payments on your studio
- Utilities and insurance premiums
- Staff wages
- Equipment leases
- Marketing costs
This coverage ensures your business can continue operating while you recover, protecting the enterprise you’ve worked hard to build.
Key Person Insurance: Protecting Your Studio’s Future
For studio owners who employ other instructors, key person insurance protects your business if you (or another key teacher) becomes unable to work. This coverage recognises that certain individuals are crucial to your business’s success and revenue.
If you’re the face of your studio, the teacher parents specifically request, or the choreographer behind your competition success, your absence could significantly impact your business. Key person insurance provides funds to:
- Hire replacement instructors
- Cover lost revenue
- Maintain business operations
- Recruit and train new staff
Other Insurance Considerations for Dance Teachers
While life and income protection insurance should be your priority, other insurance types also play important roles in protecting your teaching career.
Public Liability Insurance
This covers you if a student or visitor is injured during your classes or if you accidentally damage property. Many venues require proof of public liability insurance before allowing you to teach on their premises.
Professional Indemnity Insurance
This protects you if a student claims your instruction caused them injury or failed to meet expected standards. For example, if a student preparing for an exam claims your teaching was inadequate and seeks compensation.
Personal Accident Insurance
This provides cover for medical expenses and lost income following an accident, complementing your income protection coverage.
Equipment Insurance
Protects your sound systems, mirrors, portable barres, and other teaching equipment against theft, loss, or damage.
How Much Cover Do You Need?
Determining the right level of insurance coverage depends on your individual circumstances. Consider these factors:
For Life Insurance
- Your outstanding debts (mortgage, business loans, credit cards)
- Your family’s ongoing living expenses
- Future costs like children’s education
- Funeral expenses
- Your partner’s ability to earn income
For Income Protection
- Your monthly income and expenses
- How long you could manage without income
- Any existing savings or emergency funds
- Whether you have dependants
For Trauma and TPD Insurance
- Your mortgage and other debts
- Potential medical and rehabilitation costs
- The cost of retraining for a new career
- Your family’s financial needs
How to Make Insurance Affordable
As a dance teacher, particularly if you’re self-employed or running a small studio, budget considerations matter. Here are strategies to make insurance more affordable:
- Bundle your policies: Combining life, TPD, and trauma insurance with one insurer often reduces premiums
- Choose appropriate waiting periods: Longer waiting periods on income protection reduce premiums
- Consider stepped vs level premiums: Stepped premiums start lower but increase with age; level premiums remain constant
- Review your cover regularly: Ensure you’re not over-insured as your circumstances change
- Claim tax deductions: Income protection and business expense insurance premiums are generally tax-deductible
At Absolute Insurance, we understand the unique challenges facing dance teachers in Perth and across Western Australia. We take the time to understand your specific situation and recommend coverage that truly fits your needs. Contact us to secure your future today.
Related posts:
- What Life Insurance Do Teachers Get?
- Why Life Insurance Is Crucial for Teachers in Australia
- Top 5 Financial Risks Teachers Overlook and How Insurance Protects You
Reviewed by Greg Maguire
Greg Maguire reviewed this article to make sure the information is accurate and reflects current insurance practice. It is general advice only and does not take your personal circumstances into account.
Greg Maguire is an Authorised Representative (No. 255354) of AD Advisory Services Pty Ltd, ABN 68 005 830 802, AFSL 237058.
Related Services
Insurance for Teachers
Insurance for Teachers →
Insurance for Construction Workers
Insurance for Construction Workers →
Insurance for Healthcare Workers
Insurance for Healthcare Workers →
Insurance for FIFO Workers
Insurance for FIFO Workers →
Insurance for Miners
Insurance for Miners →
Insurance for Tradies
Insurance for Tradies →
Related Articles